Why You Can't Pause Spotify Premium, and Who Pays

Open Spotify, go to your account, and look for the button that stops your Premium bill for a month while leaving everything else in place. It isn't there. You can't pause Spotify Premium; you can only cancel it. And the person who pays for that missing button is whoever holds the bill, most of all the parent running a Family plan.
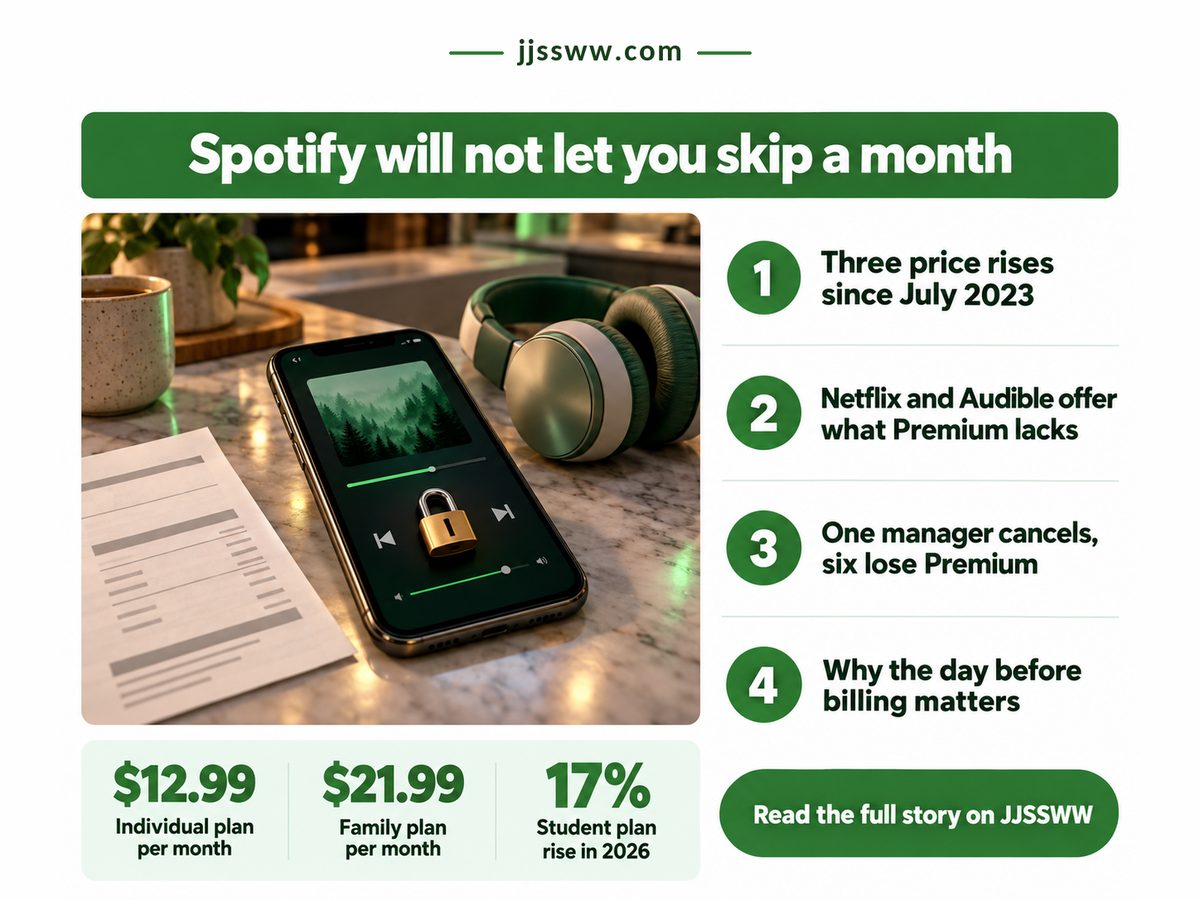
Infographic showing you cannot pause Spotify Premium, with prices and a locked phone

Netflix built one. So did Audible. Spotify, which keeps raising its US prices, hasn't, and the gap gets more expensive with every rise.

Key Takeaways: Spotify has no pause, so the only way to skip a paid month is to cancel before your billing date, which is safe for your playlists but not for anyone else on your plan.

  • Premium keeps running until the next billing date, so cancelling early costs you no paid days.
  • Your playlists and saved music stay on the free tier.
  • When a Family or Duo manager cancels, every managed account drops to the ad-supported free plan.
  • A cancelled free trial cannot be restarted, so finish it first.

Can you pause Spotify Premium?

No, Spotify Premium has no pause option: Spotify's own cancellation help lists only cancelling or switching plans, so skipping a month means cancelling and later subscribing again at whatever the price is by then.

That last clause is where the missing button starts to cost real money. A January 2026 SoundGuys report on Spotify's latest US increase lays out the history: Premium sat at $9.99 from 2011, then went up in July 2023, in July 2024 and again from February 2026 billing dates. By my arithmetic the Individual plan now costs 30% more than it did before mid-2023, so every month you can't skip is a dearer month than it used to be.

The usual advice is to keep paying, because cancelling feels like losing something. That advice is out of date. Spotify's cancellation page (retrieved 5 October 2026) says Premium runs until your next billing date and you keep your playlists and saved music. For a solo listener, cancelling costs almost nothing.

Spotify isn't alone in leaning on inertia: think of the Peacock and Apple TV price hikes ten days apart this August, or the scattered Google subscriptions that keep running because each bill is too small to chase.

Four numbers decide whether a break is worth it. Three come from that SoundGuys report, the fourth from Spotify's cancellation rules.

Premium Left After Cancelling

Up to 1 month

Paid days are never forfeited

Individual Plan, Monthly

$12.99

$155.88 a year, no breaks

Accounts on One Family Bill

Up to 6

One cancel moves them all

Student Plan Price Rise

17%

Hardest on the tightest budgets

The figure on Premium after cancelling matters most, because it removes the fear of losing paid time. Cancel early in your cycle or late; the only thing timing changes is whether the next charge goes through.

"

Spotify charges $12.99 every month and offers no button for the month you don't need. That is a pricing decision, not a technical limit.

So the real choice isn't pause versus cancel. It's cancel versus paying through months you won't use, and the answer depends on which plan you hold.

What happens when you cancel Spotify Premium?

When you cancel, your paid access continues until the next billing date, then the account turns free and ad-supported, keeping your playlists and saved music but dropping any managed Family or Duo members as well.

The table prices that choice plan by plan, at the February 2026 rates SoundGuys reported. The cost figures are my own arithmetic: the monthly price times the months you would not use.

Dimension Cancel vs Keep paying What it means for you
💰 Family, 2 months Cancel $0
Keep $21.99 x 2 = $43.98
✅ The largest plan saves the most
💰 Duo, 2 months Cancel $0
Keep $18.99 x 2 = $37.98
⚠️ Only worth it if both of you agree
💰 Solo, 3 months Cancel $0
Keep $38.97
✅ What a three-month pause would save
📊 Playlists Cancel kept on free tier
Keep kept
✅ Your library survives the break
🔋 Offline play Cancel ads, no downloads
Keep ad-free, downloads
❌ Commutes and flights get worse
🧾 Family members Cancel all move to free
Keep unchanged
❌ Your break becomes everyone's break
⏱ Free trial Cancel cannot be restarted
Keep turns into a paid plan
⚠️ Stop only after you finish testing
🏁 Best suited for Cancel breaks of 1 month or more
Keep plans where others object
🏁 Solo plans win; shared plans need a vote

For one person, cancelling is close to free. For a household the saving is bigger, and so is the damage.

Which streaming services let you pause your subscription?

Several do, which suggests Spotify's omission is a choice.

Netflix. Up to 3 months. Not on Basic plans. Audible. Up to 3 months. Listed, Sep 2026. Hulu, YouTube TV. Pause offered. Sling TV as well. Spotify. No pause. Cancel or change plan.

If you want to stop paying for a while without closing your account, Spotify is the one service here where cancelling is the only route. Sources: Netflix Help Center and SubTracker's September 2026 roundup (retrieved 5 October 2026), which is not exhaustive, plus Spotify's cancellation help.

The Spotify family plan price of one person's break

The heaviest cost of a missing pause falls on whoever manages a Family or Duo plan, because one cancellation moves every managed account to the free, ad-supported tier, whether the others wanted a break or not.

Spotify's support page is blunt: if the plan manager cancels, managed accounts move to the free plan. That means ads and no offline downloads for a teenager on a school trip because a parent saved a month's fee. A pause would avoid that.

Free trials carry their own trap. Spotify says zero-priced trials can't be reactivated once cancelled, so cancelling early to be safe throws away the rest. Here I part company with the standard advice to cancel every trial on day one: with Spotify, set a reminder for the day before it ends. Some banks now let you cancel a subscription from the bank app, though only for a shortlist of merchants.

Will Spotify ever add a pause? My read, and it's opinion, is that the people who would use one are exactly the subscribers Spotify most wants to keep billing. I'd like to be wrong.

  • Cancel after your billing date and one more charge has already gone through.
  • Family and Duo members lose Premium together, never one at a time.
  • Coming back means paying whatever the price is then.

Cancel this month only if all of these are true for you

  • You pay for an Individual plan, or everyone on your Family or Duo plan has said yes.
  • You expect to skip at least one full billing cycle.
  • You are not inside a free trial you still want to use.
  • You can live with ads and no offline listening until you come back.

Open Spotify's account page today, note your next billing date and set a reminder for the day before. If the card above describes you, cancel then: you keep every paid day, your playlists wait, and the next charge never arrives. If not, keep paying.
Cancel Subscription From Bank App? Only Sometimes

Open your banking app and try to kill a charge from inside it. For most of the subscriptions sitting on your card, the app will not let you. It shows the charge, sometimes a tidy list of every recurring payment, then hands you instructions pointing back at the merchant's own website. That is the missing feature, and you pay for it in the months between spotting a charge and actually stopping it. Cancel subscription from bank app works now, but only sometimes, and only for names big enough to make a list.

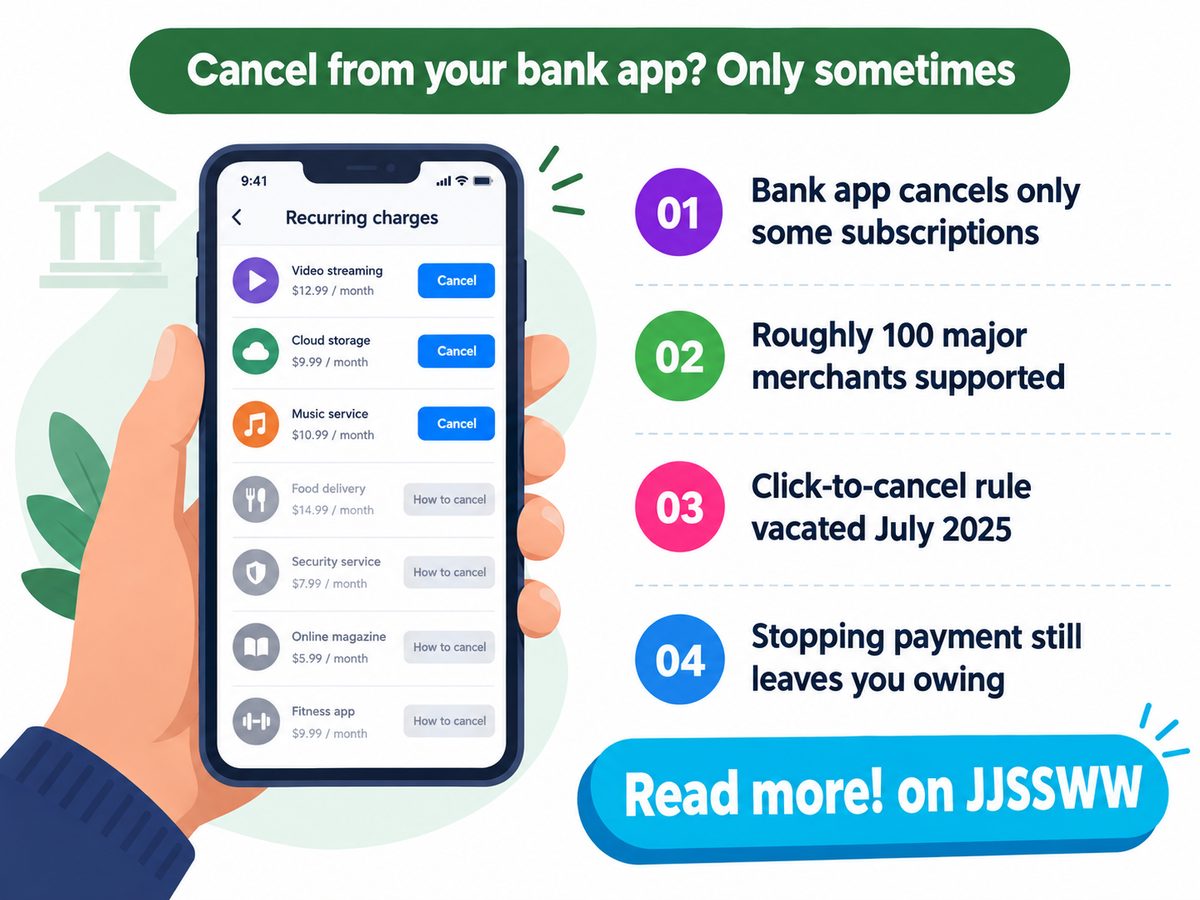
Cancel subscription from bank app panel showing listed and unlisted recurring charges

Key Takeaways: your bank app can end some subscriptions for you, and the rest are still your job.

  • Visa's cancel panel reached North American issuers through summer 2026, one bank at a time.
  • Coverage is a merchant list, so anything off it gets instructions rather than a cancellation.
  • No federal rule has forced merchants to accept your exit since July 2025.
  • Blocking a payment is not ending a contract, and you still owe the money.

Can your bank cancel a subscription for you?

Sometimes, and only if your card network and your issuer have both shipped the feature and the merchant sits on their supported list, which covers big names rather than the whole of your monthly billing.

Visa announced Enhanced Subscription Manager on 26 March 2026 and said it would reach North American financial institutions through summer 2026, with Latin America and the Caribbean to follow. Inside the banking app you can see every recurring payment, and for a listed merchant you can end it outright. The button therefore arrives on your bank's schedule rather than yours, so two neighbours paying the same streaming bill can have completely different options this month.

This is a deposit retention feature before it is a consumer protection. Or rather, it is both, and the order matters, because the merchants big enough to make someone switch banks get wired in first and the small biller you forgot about does not. Anyone who has watched streaming price rises land quietly on a card statement already knows which charges go unnoticed, and they are rarely the famous ones.

And the reason your bank is offering this rather than the merchant being made to accept your cancellation is that the federal version died. The Eighth Circuit vacated the FTC's click to cancel rule on 8 July 2025 in Custom Communications v. FTC, because the agency skipped the preliminary regulatory analysis required once its own judge found the rule would cost the economy more than $100 million. It had been due to apply on 14 July. So the exit right you were within a week of having never applied at all, and the substitute is a product feature your bank can scope however it likes.

Put those dates next to the rollout and you get the figure that actually describes your position: roughly twelve months ran between the death of the federal exit right and the first in-app cancel buttons, and longer if your issuer sits in a later wave. That subtraction is ours, not a finding from either source. Four other numbers decide whether you can hand the audit to your bank at all, and they come from the court timeline above, the FTC's Amazon refund program, Mastercard's October 2025 work with U.S. Bank, and Deloitte's 2026 Digital Media Trends, fielded in late 2025 with 3,575 respondents.

Federal cushion

6 days

Your exit right never applied.

Price of blocked exits

$2.5B

Repaid years after billing.

Charges per person

8+

More billers than any list.

Yearly churn rate

40%

You quit something most months.

Churn at that level is the part people underestimate. Leaving a service is not an annual chore you can batch, it is a habit, and a panel covering part of your stack means carrying two systems in your head: the one where a few taps end a charge, and the one where you log in somewhere else and hunt for a confirmation email. Anyone already paying for subscriptions scattered across one company's products has met the second system. My own read, and it is a stance rather than a finding, is that issuer merchant lists will grow slowly once the retention win is banked, so I would not wait for yours to cover everything.

"

Six days. That is the entire life of a federal right to cancel the way you signed up, which is why the exit you use now belongs to your bank instead of to you.

Cancel subscription from bank app: what works and what does not

Two paths sit behind one panel, and the difference is whether the merchant is on your network's supported list, because a listed merchant gets a real cancellation while everything else gets a guided workflow you finish yourself.

The table sets the two paths against each other, using the numbers each network has published plus one threshold that is ours rather than theirs. Read the last column first if you are in a hurry.

CategoryListed merchant, cancel in appEverything else, guided workflowWhat it means for you
Coverage100 plus major merchants via Visa's Digital Enablement SDKThousands of smaller billers, instructions onlyOpen the panel and check before you trust it with a charge
Network reachMastercard with U.S. Bank: hundreds of participating merchants since 15 October 2025Any biller outside those dealsYour card brand decides the option, not the service you pay
Proof of exitStatus shown in the app, usually same sessionOnly the merchant's own confirmation countsSave the email or you hold no evidence at all
Why it exists72% want to manage subscriptions in banking app menusMerchants keep the exit on their own termsCoverage stops where the deposit win stops
Legal backingNone, a product feature your issuer can withdrawState law only: California since 1 July 2025, plus New York and MassachusettsOutside those states your exit is whatever is offered
Contract effectEnds the recurring payment mandate on the cardEnds the agreement only once the merchant records itStop a charge without cancelling and you still owe the balance
Exit trigger$5 on a $69 monthly bill, about 7%, is where 61% say they quitSame trigger, slower exitPrice rises reach you faster than the button reaches your bank
Best suited forAnyone whose biggest charges are household namesAnyone billed by small services and app storesMost people need both paths, so keep your own list

Read down that last column and the pattern is blunt. The panel is genuinely useful for the handful of charges that are household names, and close to useless for the ones you are most likely to have forgotten. Which is backwards. Forgotten charges are the expensive ones.

Refunds ordered for failed cancellations: $1.5B. $845M paid by September 2026. $655M still waiting. Share that has reached customers: about 56 percent. Time since the settlement: about one year.

Waiting for a regulator to give you your money back is not a cancellation plan, because a year after the largest order of its kind barely half the money had reached people. Figures come from the FTC's Amazon refund program, and the 56 percent share plus the unpaid remainder are our own arithmetic.

Where the in-app cancel button leaves you exposed

The exposure sits in the gap between stopping a payment and ending an agreement, because your bank can block the money while the merchant keeps billing you on paper and eventually sends the balance to collections.

How to stop automatic payments without leaving a debt behind

The CFPB is blunt about the order of operations. Revoke the authorization with the company, then tell your bank in writing. Keep copies of both. A stop payment order can carry a fee, and the agency's own guidance says cancelling an automatic payment does not cancel what you owe. So the cancel button is only ever as good as the merchant's willingness to record the request, which is precisely the duty the vacated rule would have imposed. Regulators have started treating that friction as a design choice rather than an accident, which is the thinking behind the dark pattern rules now aimed at cancellation flows.

Scale the problem up and you reach the Amazon case. The FTC's settlement covers customers who tried to cancel through the online flow and could not, in a window running from 23 June 2019 to 23 June 2025, six years in which every charge cleared on time while the refunds did not exist yet. Signing up keeps getting easier too, and shopping agents that hold your card details will happily add one more mandate you did not diary.

  • Your issuer may not have switched the panel on, so check it before you rely on it.
  • App store billing sits outside your card, which puts it beyond the panel's reach.
  • A cancellation the app marks as done is not proof; the merchant's email is.
  • A stop payment can cost a fee and still leave the agreement running.

Four things to check about your own account this week

  • Your banking app shows a recurring payments screen, and a cancel control actually appears on it.
  • The service you want gone bills your card directly, not through an app store account.
  • Your state has an auto renewal law you could cite if the merchant argues.
  • Your last cancellation left a written confirmation you can still find today.

So do the work the panel cannot. Open your bank app this week, write down every recurring charge it lists, and mark the ones it will not cancel for you, because those are the ones needing an email trail and a date in your calendar. The decision in front of you is narrow: either you keep your own cancellation list, or you accept that part of your stack bills on until you happen to notice. Keep the list.

TRAI Complaint Online, And Who Actually Fixes It

Your broadband has been dead since Thursday. You have called the helpline four times, been promised a technician twice, and nobody has come. So you do the sensible thing and search for how to file a TRAI complaint online, because TRAI is the regulator and regulators fix things. That search is where most people lose the next three weeks.

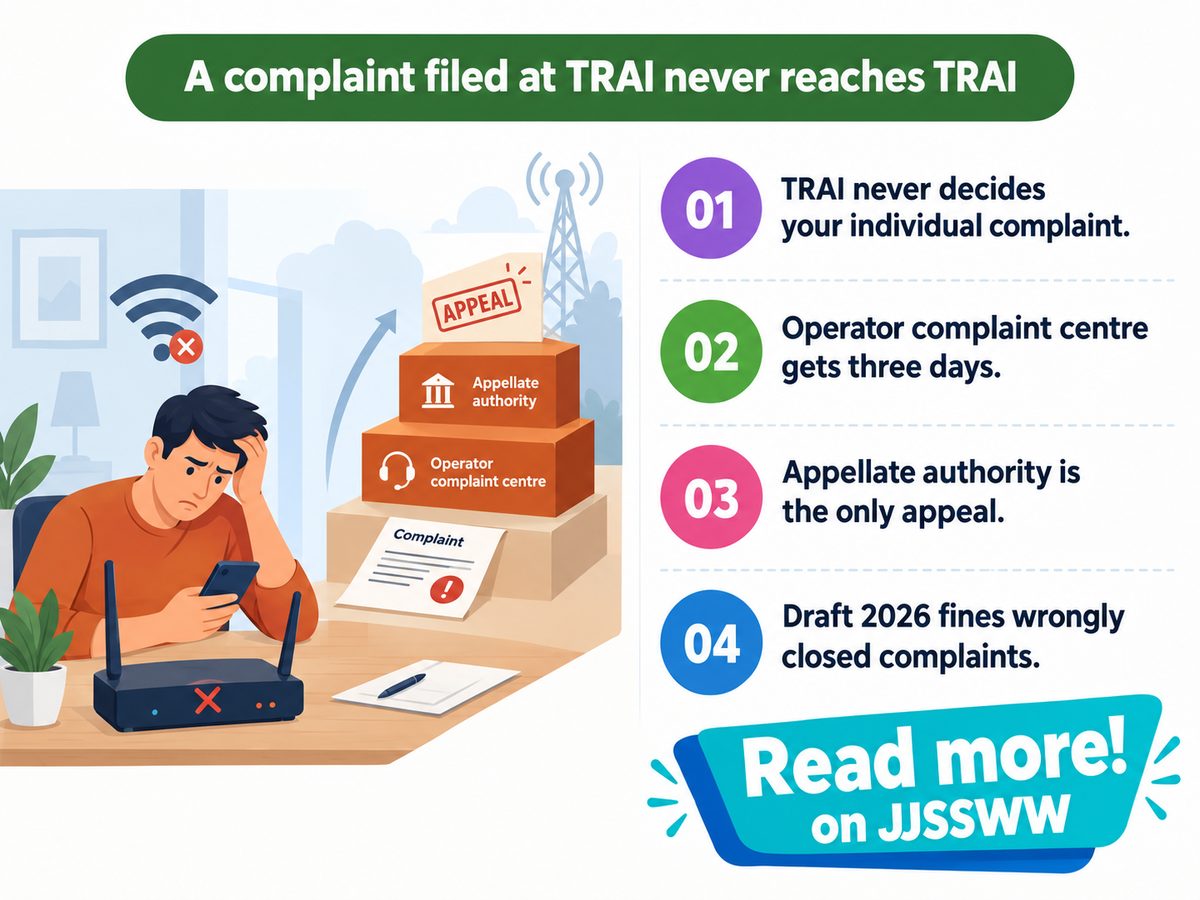
Escalation ladder diagram showing the trai complaint online route from operator to appellate authority

Here is the sentence that changes the plan, and it sits on TRAI's own FAQ page: "It is clarified that individual consumer complaints are not handled by the TRAI." Not a policy position buried in an annexure. One plain line on the regulator's website. TRAI writes the rules your operator has to follow and audits whether they followed them. It does not read your ticket, or rather, it reads the aggregate of everyone's tickets once a quarter, which is a very different thing from reading yours.

A complaint filed at TRAI does not go to TRAI, and it never has.

  • Your operator's complaint centre is the only body with a deadline to fix your problem.
  • When that deadline lapses, the appellate authority inside the same operator is your second and last regulated step.
  • A draft amendment dated 7 May 2026 would fine an operator every single time it closes a complaint improperly.
  • That draft has not been notified. Until it is, you are working the rules written in 2012.

How Do You Complain To TRAI, And Where Does It Go?

You do not complain to TRAI. You complain to your operator's complaint centre, which owes you a resolution inside three days where no other quality of service timeline applies, and then to that operator's appellate authority.

That distinction sounds like bureaucratic hair splitting until you look at how many people trip over it. In Semrush's India database, retrieved on 7 September 2026, the phrase "trai complaint" pulls roughly 3,600 searches a month and "trai complaint online" another 880. Most of those people are typing the name of the one organisation in the chain that will not act on their case. They are not being stupid. They are being logical, and the system is not.

The standard advice on consumer forums is to escalate to TRAI when your operator stonewalls you. It is wrong, and it has been wrong since the parent regulation was notified on 5 January 2012. What TRAI actually gives you is a map: the Telecom Consumer Complaints Monitoring System lists every operator's complaint centre and every appellate authority, circle by circle. A map is useful. It is not a judge.

This has the same shape as the enforcement gap behind India's dark pattern crackdown and what it actually changed for online shoppers. A rule exists, the body that enforces it sits somewhere the consumer does not expect, and the distance between those two facts is where people give up. Billing disputes follow the pattern too, which is why the specific dates behind staggered streaming price increases and when your bill actually changes end up mattering more than the headline price.

The numbers below are the ones worth holding on to before you decide how much of your week this is worth.

Age of the ladder

14 years

Unchanged since January 2012

Late report ceiling

Rs 10 lakh

Cap on delay charges, draft

Monthly searches

3,600

For "trai complaint" in India

Daily meter

Rs 20,000

Per day after the first fortnight

The money that will actually change operator behaviour is not the per case fine. It is the daily meter on late quarterly performance reports, because that one runs whether or not a single consumer complains. A per complaint charge only bites when somebody appeals and wins. A reporting clock bites on a calendar, which is much harder to manage away, and finance departments respond to calendars.

"

TRAI says it in one line on its own website: individual consumer complaints are not handled by the TRAI. Every wasted week that follows starts with not reading that sentence.

So what would actually change if the draft on the table becomes law?

What A TRAI Complaint Online Costs You In Days

Under the rules in force, a complaint that runs the full distance can take about 72 days, and up to 132 if the appeal window is extended. The draft compresses that to about a month.

The document is formally the Telecom Consumers Complaint Redressal (Fourth Amendment) Regulation, 2026, dated 7 May 2026, and stakeholder comments closed on 5 June 2026. It leaves the two tier structure alone and goes after the two things that make the structure fail in practice: how easily you can get a complaint registered at all, and what it costs an operator to close one that should have stayed open.

What ChangesIn Force TodayDraft Of 7 May 2026
DecisionOperator's complaint centre, then that operator's appellate authorityUnchanged, and TRAI still decides no individual case
ChannelsFive: IVRS, web portal, email, post, in personSeven, adding a mobile app and chatbots or AI agents
ComplaintNo penalty specified for closing one improperlyRs 1,000 for each improperly dismissed complaint
AppealNo penalty specified for dismissing one improperlyRs 5,000 for each improperly dismissed appeal
CeilingNone, because no per case charge existsRs 50 lakh per licensed service area per quarter
ReportingNo standing duty to publish complaint performanceA Consumer Corner carrying quarterly performance reports and survey results
Best Suited ForA complainant with up to three months of patienceA complainant who needs an answer inside one month

Those totals are our own arithmetic, not a figure TRAI publishes. Add the three day resolution window to the thirty day appeal window and the roughly thirty nine days the appellate authority currently takes, and you get about seventy two days end to end. Stretch the appeal window to its ninety day maximum and the same journey runs past four months. The draft cuts the appeal window to fifteen days and caps the appellate decision at fifteen more, so the same journey lands near thirty three. The trade is real and it is not free: you gain speed at the far end and lose half the time you had to notice the deadline in the first place.

Day 0. Day 3. Day 18. Day 33. You file, docket number issued. Operator's own deadline lapses. Last day to file your appeal. Appellate ruling falls due.

Day markers are our arithmetic on the limits stated in TRAI's Draft Telecom Consumers Complaint Redressal (Fourth Amendment) Regulation, 2026, dated 7 May 2026.

How Do You Register A Complaint Against Airtel Or Jio?

The same way for either one. Every licensed operator has to run a complaint centre and name an appellate authority for each licensed service area, and you can look both up on TRAI's TCCMS portal before you file anything.

The brand on the bill changes nothing about the procedure, which is the useful part and also the frustrating part. There is no shortcut for a big operator and no penalty box for a bad one, at least not yet. What varies is how easy each company makes it to reach a human, and that variation is precisely what the draft's Consumer Corner would expose to anyone willing to read a quarterly report.

Worth saying plainly: I think the appeal window cut is the weakest idea in the draft. Fifteen days sounds tidy on paper. In practice a complaint that was quietly closed while you were travelling can burn most of that window before you notice, and the fix costs nothing to write. Keep the thirty day window and cap the decision at fifteen. You would get the speed without moving the risk onto the person with the least information, which is the same imbalance running through the case for and against handing AI shopping agents your wallet. The pattern repeats wherever a process is designed by the party that already knows how it works. Subscription billing does it too, as Google's scattered subscriptions and what they quietly cost shows.

Four things to watch for once you are in the process:

  • A ticket marked resolved without your agreement still starts the appeal clock. The draft would make the confirmation message and its survey link the marker of closure, which helps only if you actually read the message.
  • The appellate authority sits inside the operator. It is not independent and there is no separate ombudsman waiting behind it.
  • Consumer courts stay open to you, but that is a different process with its own fees and calendar, and the telecom ladder does not feed into it.
  • If the problem is unwanted calls or messages, that runs on the Do Not Disturb rules and a separate register, not on this ladder at all.

Do these before you need any of it.

Ask for the docket number. Say it out loud on the call. Without one, nothing you claim later carries a date.

Write down the filing date. Every deadline in the current rules and in the draft counts forward from that one day.

Keep the closure message. The draft turns an improper closure into a chargeable event, so that message becomes the case.

Do one thing this week, before anything breaks. Open TCCMS, find the appellate authority listed for your operator in your circle, and save the name and address where you will find it in a hurry. The ladder only works for people who know it exists, and the regulator has spent fourteen years assuming you would look it up.